Good debt vs. bad debt matters because one type funds growth while the other erodes margins and flexibility. Good business debt increases future cash flow or net worth and returns more than its total cost. Bad business debt funds losses, consumption, or assets that don’t pay back. This guide gives clear rules, simple metrics, and concrete tactics business owners can use in 2026 to decide when to borrow, when to stop, and how to fix mistakes without guesswork.
Key Takeaways
- Good debt in business funds assets or initiatives that generate more cash flow than the loan cost, driving growth and profitability.
- Bad debt funds losses or consumption, often carrying high interest and fees that shrink margins and reduce financial flexibility.
- Evaluate business debt with metrics like Debt Service Coverage Ratio (DSCR), ROI, loan term alignment with asset life, and total all-in cost to ensure responsible borrowing.
- Effective debt management involves prioritizing repayment of high-cost debt, refinancing to lower interest rates, and stopping the use of credit as a recurring operating solution.
- Business owners should borrow only for projects with documented demand, measurable cash-flow benefits, and a positive return on investment to maintain healthy finances.
- Embedding debt evaluation and planning into regular financial forecasting protects business growth and avoids costly borrowing mistakes.
What Good Debt Looks Like For Business Owners
Fact first: Good business debt funds an asset or initiative that produces more cash than the loan costs. Good debt is planned, tied to a measurable outcome, and repaid comfortably from the project’s incremental cash flow.
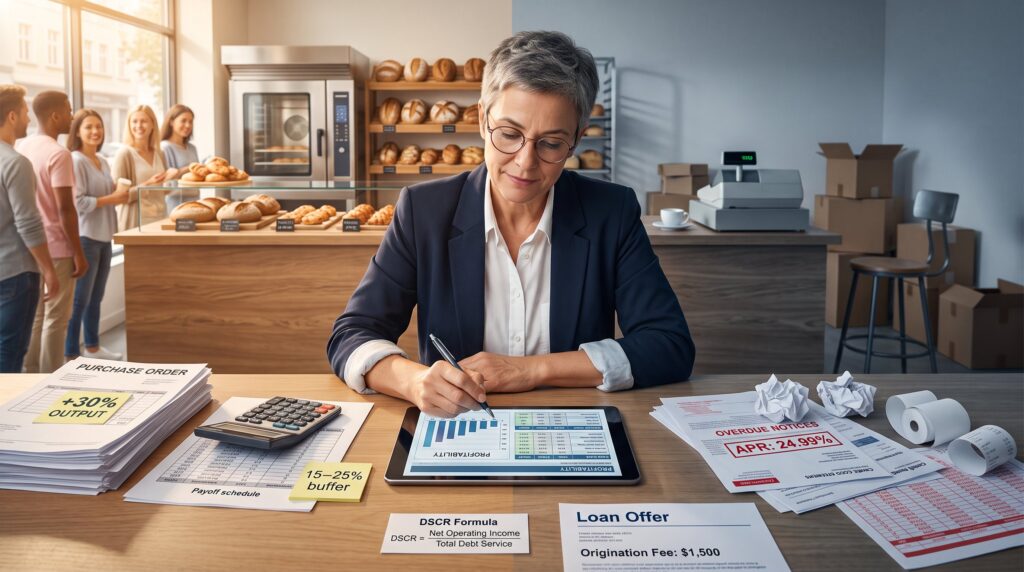
A specific example: a bakery borrows $40,000 at 8% to buy a second oven that increases weekly output by 30% and cuts unit labor by 12%. If the extra sales and lower cost pay for the loan plus a profit margin within 18 months, that borrowing is good debt. Good debt often shows these signals: predictable demand (signed orders or repeat customers), a time horizon matched to the asset’s life, and modest interest and fees that don’t eat working capital.
When assessing new borrowing, owners should verify three things quickly: a clear revenue lift estimate, a conservative payback timeline, and an affordability check showing loan payments leave at least a 15–25% buffer on monthly cash flow. For owners who want a primer that ties debt choices to counseling and legal support, see the foundation’s debt relief overview for related services and resources.
What Bad Debt Looks Like For Business Owners
Fact first: Bad business debt funds losses, consumption, or assets that provide no lasting revenue and cost more than they earn.
A concrete pattern is easy to spot: a retailer using a 24% APR card to pay routine payroll: each month interest grows while margins shrink. Another pattern: repeatedly taking short advances to make prior loan payments, this “borrowing to pay borrowing” loop signals structural cash-flow mismatch. Bad debt also shows these red flags: high origination fees, annual account charges, and payments that require dipping into reserves.
Owners who face these symptoms should treat them as urgent. The next section lists specific red flags and common examples so owners can quickly classify their liabilities before the problem compounds.
Simple Metrics To Evaluate Debt Quality (Cash Flow, ROI, Term, Cost)
Fact first: four metrics give a fast, defensible decision: cash-flow coverage, ROI, term match, and total cost of capital.
Cash-flow coverage. Compute Debt Service Coverage Ratio (DSCR) = Net Operating Cash Flow ÷ Annual Debt Service. A DSCR below about 1.25 signals danger. For example, a small manufacturer with $120,000 net cash and $100,000 of annual debt service yields a DSCR of 1.2, this is thin and needs rework.
ROI. Compare incremental profit from the financed activity to the loan’s total cost. If a $30,000 loan (total cost $3,600 interest) enables $90,000 of new sales with 20% margin ($18,000 gross profit), ROI is positive, good debt. If incremental profit is less than total interest and fees, it’s bad.
Term match. Match the loan term to asset life. A seven-year equipment loan for a two-year lease is mismatched and risky.
Cost of capital. Include APR, origination fees, prepayment penalties, and ancillary charges. A headline 8% rate might be 11% after fees: always compute the all-in rate over the term.
These metrics let owners score each borrowing and compare options objectively. For owners building stronger planning habits, the site’s piece on business financial plans explains how to embed these metrics in regular forecasting.
Practical Strategies To Manage, Convert, Or Avoid Bad Debt
Fact first: convert expensive, unproductive debt into longer-term, lower-cost facilities where possible and stop using credit as an operating bandage.
Tactics that work: prioritize repaying the highest-cost debt first, then refinance remaining balances into structured loans when cash flow supports predictable payments. For example, swapping a $50,000 24% credit-card balance into a two-year loan at 9% can cut annual interest from $12,000 to roughly $4,500, freeing $7,500 to reinvest.
Stop-gap fixes: pause nonessential spending, renegotiate vendor terms, and tighten collections to boost cash flow. Longer-term fixes: revise pricing, reduce variable overhead, and create a 6–12 week cash cushion so owners don’t use debt for recurring gaps. A disciplined borrowing rule helps: only borrow for projects with documented demand, quantified cash-flow impact, and positive ROI after all costs.
Operational help resources on the site, like the article about financial planning and legal exposure, outline processes owners can adopt to avoid repeating mistakes. For owners considering consolidation options, the site’s debt consolidation Q&A lists key questions to evaluate offers.
Conclusion
Insight: Debt is a tool, used well it accelerates growth: used poorly it destroys optionality. Business owners should evaluate borrowing with cash-flow coverage, ROI, term match, and all-in cost. When mistakes happen, act fast: refinance expensive balances, stop borrowing for recurring gaps, and embed debt checks into regular financial planning. Small, transparent rules and realistic forecasts protect growth and keep debt working for the business, not against it.