How to Use Financial Counseling Articles to Build a Practical Budget starts with one clear promise: turn readable guidance into a working monthly plan. Readers often save article links and never act. This guide shows how to pick credible pieces, pull concrete rules, translate percentages into numbers, and iterate as circumstances change. The steps are practical, evidence‑aware, and tied to real examples so a reader can finish with a usable budget for the next pay period.
Key Takeaways
- Financial counseling articles offer trusted, actionable advice to build a practical monthly budget tailored to real-life income and expenses.
- Evaluate article credibility by checking author credentials, recent publication dates, and cited primary sources before applying financial advice.
- Extract clear rules, checklists, and examples from articles, then convert percentages and guidelines into specific dollar amounts for your budget.
- Automate transfers for savings and debt repayment to reduce friction between reading advice and taking consistent action on your budget.
- Regularly review and update your budget quarterly using new financial counseling articles to adapt to changing rates, laws, and personal circumstances.
- Maintaining a folder of trusted articles and resources helps ensure your budget remains aligned with current best practices and financial conditions.
Why Use Financial Counseling Articles To Build Your Budget
Articles from financial counseling sources provide focused, timely steps that map directly onto household choices. They break complex topics, income, fixed and variable costs, debt payoff, emergency funds, into checklists readers can follow. For example, a counseling piece may recommend prioritizing high‑interest debt while keeping a three‑month emergency fund: that single recommendation converts into a monthly transfer and a reduced credit balance target. Using articles saves time: instead of parsing regulations and bank terms, readers apply vetted rules of thumb and current best practices. Articles also surface market changes and product shifts, interest rate updates or new assistance programs, that affect monthly numbers. When readers treat articles as modular inputs (rules, examples, templates), they cancel confusion and create budgets that respond to changing advice, rather than staying stuck on outdated assumptions.
How To Evaluate Credible Financial Counseling Articles
Start with the fact: not all finance articles are trustworthy. Credible pieces show author credentials, cite primary sources, and publish recent dates. Readers should confirm an author is a CFP, accredited counselor, academic, or experienced journalist who links to government reports or academic studies. Publisher quality matters: reputable institutions and university sites tend to have editorial review. Verify data by checking linked sources and the publication date, prefer content updated within the last year for rate‑sensitive topics.
Practical check: open an article and find three anchors, author bio, at least one primary source link, and a date. If any are missing, treat the guidance as tentative and look for corroboration. This quick vetting prevents following outdated or biased recommendations that could misallocate monthly funds. For deeper reading on how counseling, debt relief, and legal resources intersect with budgeting, consult the site guide to debt and counseling resources.
Red Flags And Trust Signals To Look For
Red flag first: promises of unrealistic returns or urgent “act now” pressure. Those articles push products, not budgets. Other warnings: vague “studies show” references without links, undisclosed sponsorships, or advice that only promotes a single product. Trustworthy signals are transparent author bios, disclosed conflicts, and multiple independent citations that link to primary data.
A practical test reads like this: does the article explain assumptions? Credible pieces state interest rates, timeframes, and sample incomes. If an article recommends saving 20% but shows no sample income or timeline, it is less useful. Conversely, a trustworthy article might show a real example: a household earning $3,000 net allocating $600 to savings and $300 to debt. Those concrete numbers are directly transferable into a monthly budget and reduce guesswork.
Extracting Actionable Advice: What To Pull From Articles
Answer first: pull rules, checklists, and examples. Articles often include concrete rules, “save 10–20%,” “pay extra on >12% APR debt,” or “keep three months’ expenses.” Extract those as actionable items and convert them into budget line items. Also copy checklists for tracking: daily spending logs, weekly bill calendars, and monthly reconciliation steps.
Next, harvest templates and tables. If an article gives a sample budget or table, map its categories to the reader’s own income and bills. Use article language as labels, rent, utilities, groceries, minimum debt payment, so categories remain consistent across sources. Finally, capture decision rules: when to consolidate, when to pause investments to pay down debt, or how to prioritize emergency savings. Those rules become conditional steps in the budget: if APR >10%, allocate X extra dollars to debt until balance <Y.
Converting Advice Into A Realistic Monthly Budget
Core fact: convert percentages and rules into fixed monthly numbers. Start with net monthly income, then assign mandatory expenses, savings, and discretionary spending. Use article guidance as percentage rules, then translate those to the actual dollar amounts for the month.
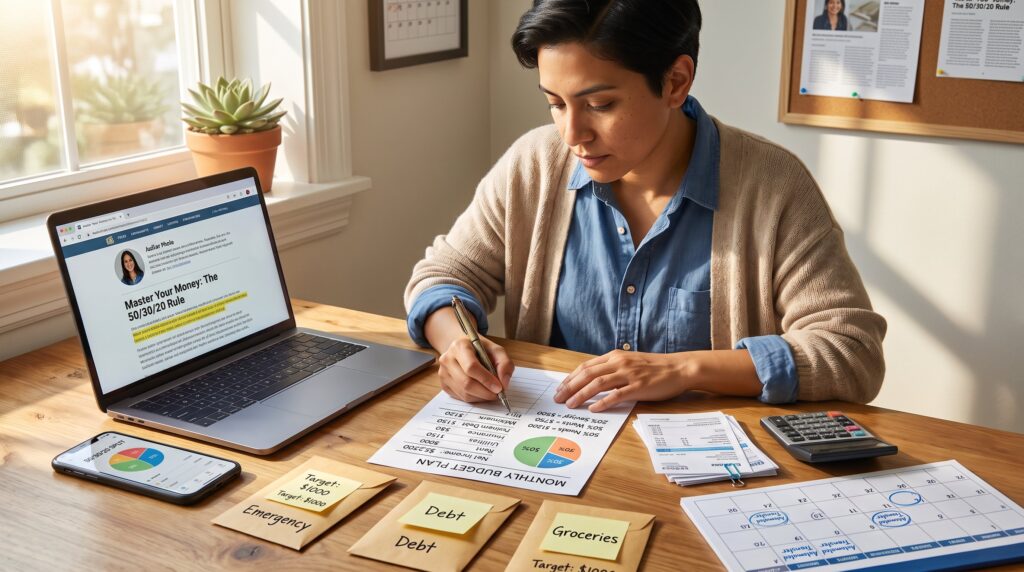
A practical framework is 50/30/20 or a tailor made split recommended by counselors. If articles suggest an emergency fund be funded first, move a defined percentage, say 10%, until the fund reaches the target. If an article prioritizes paying high‑interest debt, designate a separate debt line in the budget and automate transfers. The key is discipline: automated transfers and labeled accounts remove friction between reading and doing. When uncertainty remains, compare article recommendations against an official guide like Investopedia’s monthly budgeting approach to validate category choices and ensure no common expense is overlooked.
A Simple Step-By-Step Example To Turn Article Tips Into Numbers
Fact first: a small, specific example makes the process repeatable. Assume net monthly income = $2,500. Mandatory costs: rent $900, utilities $150, insurance $80, minimum debt $120. That leaves $1,150. Apply article rules: 20% to savings/debt ($500), 50% to needs (already mostly covered), 30% to wants ($750 cap). The actionable steps:
- Automate $300 to a high‑interest credit card payment (above minimum) and $200 to an emergency savings account. 2. Move $100 weekly to a groceries/household fund to control variable spending. 3. Track every expense for 30 days using a simple spreadsheet or a budgeting app referenced in counseling pieces.
This example mirrors common counseling rules and shows precise transfers, not vague advice. Readers who follow these numbers will see the emergency fund grow by $200 monthly and the credit balance fall by $300 monthly, measurable progress tied to article guidance. For further tactics on sticking to a plan, review the site’s practical budget guides such as the article on how to build a budget.
Adapting, Reviewing, And Improving Your Budget With Ongoing Articles
Key insight: budgets must change as rules, rates, and life events change. Readers should schedule quarterly reviews and an annual reset. During a review, compare actual spending against the budget and consult recent counseling articles for updated best practices on debt treatment or saving targets.
When laws or interest rates shift, articles often recommend changing strategies, e.g., pause investments when rates spike or refinance when consolidated offers appear. Link topical pieces to action: if an article on lifestyle inflation warns of creeping wants, adjust the wants category and increase automation to savings. For practical continuity, build a bookmarks folder of trusted pages and include cluster articles from the site such as budget planning software and emergency fund basics. These references help validate decisions and keep the budget aligned with current counseling recommendations.
Conclusion
Turning financial counseling articles into a practical budget requires selective reading, concrete extraction of rules, and disciplined translation into dollar amounts. By vetting sources, copying checklists, automating transfers, and reviewing quarterly, a reader moves from information to measurable progress. The real work is in the follow‑through: act on one article’s rule this pay period and test the result next month.