Homeowners insurance claims 21 strong foundation disasters must start with clear knowledge. The reader should know their policy, limits, and exclusions before a loss. This guide lists steps that help a homeowner file claims and protect recovery. It uses direct language and specific actions. The reader will get a practical path they can follow after a disaster.
Key Takeaways
- Understanding your homeowners insurance policy, including coverage limits and exclusions, is essential before disaster strikes to ensure effective claims handling.
- Immediately prioritize safety and take reasonable steps to mitigate further damage after a loss, then report the claim to your insurer promptly.
- Thoroughly document all damage with photos, inventories, receipts, and time-stamped records to support a strong homeowners insurance claim.
- Follow a structured 21-step checklist that groups emergency response, documentation, and reporting tasks to streamline the claims process.
- Avoid common pitfalls like delayed reporting, poor documentation, and disposing of damaged items before adjuster inspection to protect your claim rights.
- Review settlement offers carefully and seek independent appraisal or professional advice if coverage is denied to maximize recovery from homeowners insurance claims.
Understand Your Policy Before Disaster Strikes
Homeowners should read their policy and note covered perils, limits, and deductibles. He should mark policy numbers and company contacts where he can reach them quickly. She should check endorsements for flood, earthquake, or sewer backup. They should compare replacement-cost and actual-cash-value rules. The homeowner should list out-of-pocket limits and claim timelines. The homeowner should store a copy of the policy in the cloud and in a safe physical place. Homeowners insurance claims 21 strong foundation disasters returns value when policy details match real needs.
Immediate Actions After A Loss: Safety, Mitigation, And Reporting
They must prioritize safety first. He should call emergency services for injuries or fire. She should shut off gas and electricity if safe to do so. The homeowner should take reasonable steps to prevent further damage, like covering broken windows or moving valuables. They should report the loss to the insurer as soon as possible and record the claim number. The homeowner should ask the insurer about temporary housing and payments. Homeowners insurance claims 21 strong foundation disasters benefit from fast reporting and clear safety actions.
Document Damage Thoroughly: Photos, Inventory, And Time-Stamped Records
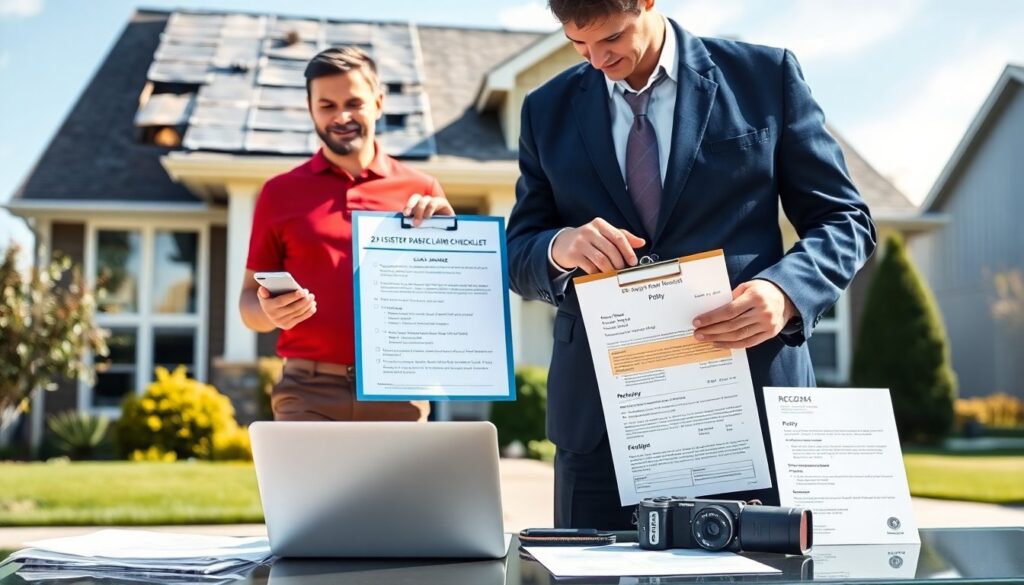
The homeowner should photograph all damage from multiple angles and create time-stamped records. He should make a room-by-room inventory that lists items, purchase dates, and values. She should keep receipts for emergency repairs and for hotel stays. They should save communications from contractors and adjusters. The homeowner should photograph serial numbers and damaged structural elements. Homeowners insurance claims 21 strong foundation disasters improve when documentation is clear, dated, and complete.
The 21-Step Claims Checklist (Grouped For Faster Action)
Homeowners insurance claims 21 strong foundation disasters require a plan that breaks tasks into clear groups. The checklist below groups steps to speed up recovery and reduce errors. The homeowner should follow the sequence and tick items off as they finish them.
— Steps 1–7: Emergency Response And Initial Documentation
- Ensure personal safety and call emergency services if needed. 2. Turn off utilities only if it is safe. 3. Move people to a safe location and secure temporary housing. 4. Photograph exterior and interior damage with time stamps. 5. Create a basic inventory of damaged items and note approximate values. 6. Save receipts for immediate expenses like boarding, tarps, and supplies. 7. Notify the insurer and get a claim number. The homeowner should keep copies of every receipt and file. Homeowners insurance claims 21 strong foundation disasters rely on these initial moves to avoid delays.
Common Claim Pitfalls And How To Avoid Them
A common pitfall is delayed reporting. The homeowner should report losses quickly to avoid denial. Another pitfall is poor documentation. He should photograph damage before repairs. She should not dispose of major damaged items until the adjuster inspects them, unless unsafe. They should avoid incomplete estimates and hire licensed contractors. The homeowner should read settlement offers carefully and ask questions before signing. If the insurer denies coverage, the homeowner should request a written explanation and consider an independent appraisal or public adjuster. Homeowners insurance claims 21 strong foundation disasters end better when the homeowner avoids these common errors and works methodically.