How lifestyle inflation can slow your debt payoff is direct: when income rises, spending often rises by the same or greater amount, leaving debt unchanged. This article explains why people normalize upgrades, how that behavior lengthens payoff timelines, and what concrete steps readers can use to stop the creep. The guidance that follows is practical, measurable, and written for someone who wants faster progress without giving up life’s small rewards.
Key Takeaways
- Lifestyle inflation causes spending to rise with income, slowing debt payoff by diverting funds from extra payments to recurring costs.
- Recognizing triggers like raises or bonuses helps prevent lifestyle creep from extending debt timelines and increasing interest paid.
- Pre-committing a portion of income increases—suggested as 50% to debt, 30% to savings, and 20% to upgrades—accelerates debt repayment sustainably.
- Automating extra debt payments and maintaining previous budget levels for 6–12 months after income bumps guard against spending drift.
- Adopting mindset shifts, such as reframing raises as tools for goals and applying waiting periods before upgrades, supports long-term financial discipline.
What Is Lifestyle Inflation And Why It Happens
Fact: Lifestyle inflation means spending grows as income grows, so discretionary upgrades replace savings or extra debt payments.
This pattern shows up when a raise, bonus, or two-paycheck household increases monthly disposable cash. Psychologists call this hedonic adaptation, the shiny purchase becomes the new normal within weeks, not years. Social comparison and subtle status signaling push choices: a friend’s new car or colleagues’ weekend trips become reference points. Behavioral economics adds hyperbolic discounting: people overweight immediate pleasure from upgrades versus long-term benefits like lower interest costs.
Concrete example: a person who gets a $600 monthly raise often adds $350 in new recurring costs (higher rent, streaming bundles, a car payment) and saves only $50. That leaves an extra $200 unallocated and likely spent within three months. That tiny drift multiplies across years and across households, extending payoff by months or years depending on balances and interest rates.
Why it matters now: with inflation and shifting job markets in 2026, raises feel scarcer, making each increase more tempting to spend. Recognizing the mechanism is the first step toward stopping it. For a fuller overview, see the site guide.
How Lifestyle Inflation Directly Slows Your Debt Payoff
Fact: When extra income is absorbed by higher recurring costs, less money goes to extra debt principal and interest accrues longer.
Mechanics are simple. Extra income that could become an accelerated payment instead funds a larger apartment, premium phone plan, or weekly dining out. That raises the monthly baseline, so when the original loan is repaid, the freed cash often vanishes into general spending, a phenomenon researchers call the “payment effect.” The result: principal falls more slowly, and cumulative interest paid increases.
Example with numbers: if a borrower uses a $300 raise to increase spending instead of applying it to a $12,000 credit card at 19% APR, they lose a year or more of early payoff and pay hundreds in extra interest. Redirecting half the raise to debt can cut payoff time by months.
Policy lever: automating extra payments and preserving previous budgets for a fixed period after income growth prevents the baseline from ratcheting up. Practical details and counseling resources that support this approach appear in broader guides like the organization’s pillar page on debt relief and counseling.
Recognizing Common Triggers And Behavioral Patterns
Fact: Raises, bonuses, tax refunds, inheritance, and combining incomes are the most common triggers for lifestyle creep.
Trigger patterns to watch for: resets after a promotion (anchor resetting), recurring fixed-cost ratcheting (upgrading rent or car), and reward framing (“I earned this”). Behavioral cues include immediate justification language, such as “I deserve” or “finally.” Those cues predict where money will go.
Concrete signals in a household ledger: three new subscription services within 90 days of a raise, a higher mortgage or lease, or a recurring transfer to a “fun” account that equals the recent raise. These signs often precede long-term drift.
Real lesson: someone admitted they bought a $900 couch after a bonus and then transferred the freed payment into weekend dining, within four months the couch felt routine. That vulnerable admission highlights how quickly new spending embeds as necessity.
Readers can learn negotiation and creditor-rights checks before taking on new obligations by consulting targeted how-to resources on debt questions and rights.
Practical Strategies To Prevent Lifestyle Creep While Paying Down Debt
Fact: Pre-committing portions of any income increase to debt and savings reduces the chance that extra money disappears into lifestyle upgrades.
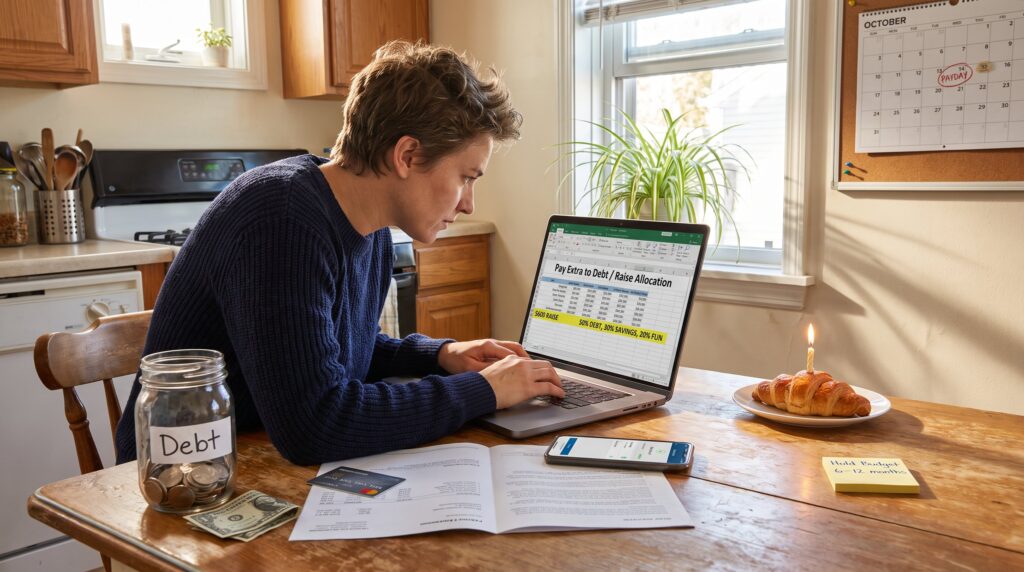
Simple rule: split raises and windfalls on receipt, for example, 50% to debt, 30% to savings, 20% for discretionary upgrades. That creates measurable momentum without forbidding small celebrations. Another effective tactic is the ‘hold period’: keep the prior budget for 6–12 months after income rises, then reassess.
Concrete tactics to carry out now:
- Automate a specific extra payment amount to creditors on payday.
- Create a “shadow payment” that keeps sending the old loan amount into a savings account after a debt clears, then direct that balance to the next target.
- Explicitly avoid new fixed obligations (car loans, longer leases) for at least six months after a raise.
For actionable help and counseling, see the organization’s comprehensive guide to debt relief and legal assistance for personalized options.
Links in this section: the pillar’s counseling overview appears naturally as a resource to plan splits and automated payments.
Budgeting Techniques And Guardrails To Protect Your Progress
Fact: Percentage rules and automation keep spending from rising in direct proportion to income.
A proven technique is to allocate fixed percentages: for instance, 20% to debt, 30% to essentials, 20% to savings, 30% to flexible spending. Another is the “pay increase ledger”: each raise generates an entry showing exactly where each dollar goes for the first 12 months.
Practical guardrails:
- Automate extra principal payments so they happen before discretionary transfers.
- Use a separate account for clearing payments to avoid temptation to spend the freed cash.
- Freeze new subscription services for 90 days following any income bump.
Concrete tool suggestion: a spreadsheet with three columns, income change, committed debt allocation, and discretionary allocation, updated on payday. Readers who want step-by-step checklists can review related posts about budget-friendly milestone rewards and broader payoff strategies to keep motivation high.
Mindset Shifts And Habit Replacements To Sustain Long‑Term Discipline
Fact: Sustained change requires replacing automatic upgrade choices with deliberate, repeatable habits.
Mindset moves that work: reframe raises as tools for goals, not automatic upgrades. Practice a 30-day waiting rule for new purchases over $150. Replace impulse upgrades with rituals that cost little, a monthly potluck instead of dining out, a secondhand furniture hunt instead of new.
Examples and vulnerable admissions: one client delayed a luxury watch purchase for 90 days and redirected those funds to a college-savings account: after three months the impulse faded and the family saved $2,400. Another admitted the hardest part was telling friends “no thanks” to weekend trips: setting a clear boundary reduced social pressure and preserved payoff progress.
For verification and techniques on avoiding lifestyle creep, reputable resources outline concrete steps and behavioral reasons behind them. Those resources support the practical strategies listed here.
Conclusion
Insight: stopping lifestyle inflation is a mix of rules, rituals, and honesty. Small, repeatable guardrails, automated payments, pre-committed splits of raises, and a waiting rule for upgrades, compound into substantially faster debt payoff. The reader who preserves even half of a modest raise for debt sees payoff timelines shorten and interest costs fall. Practical next steps: pick one rule today, automate it, and measure results monthly.