How to Check Your Rights Before Negotiating with Creditors starts with a single step: confirm whether the claim is valid before saying a word. Many people pause when a collector calls: a quick rights check prevents costly admissions, preserves statute-of-limitations defenses, and creates leverage during negotiation. This guide gives clear steps to gather records, verify who actually owns the debt, use dispute rules, and protect legal rights before making offers or payments. Readers will get concrete actions they can take now, what documents to collect, and when to bring a lawyer into a case.
Key Takeaways
- Before negotiating with creditors, always verify the validity of the debt to avoid costly mistakes and preserve your rights.
- Gather all relevant documents such as account statements, contracts, and correspondence to support your position during negotiations.
- Identify precisely who owns the debt and who is contacting you, and request verification via certified mail if there is any doubt.
- Understand your legal protections, including the statute of limitations and your right to dispute debts within 30 days of notice.
- Do not make payments or admit to the debt until you confirm the collector’s authority and the debt’s legitimacy.
- If verification fails, the debt is disputed, or legal action is imminent, seek professional legal advice promptly to protect your rights.
Why Checking Your Rights Matters Before Any Negotiation
Fact: Verifying rights first often changes the outcome, it can stop collection, expose errors, or reveal time-barred claims. When a collector calls, many people feel pressured and admit the debt. That admission can restart the clock in some states or be used in court. Checking rights gives a concrete goal: confirm the account, the amount, and the collector’s authority before responding.
Why this matters in practice: a borrower who spent 45 minutes reviewing statements found a $1,200 billing error and avoided paying it. Another person discovered the collector lacked chain-of-title paperwork and got the call to stop. Those are not rare stories: they reflect how documentation and knowledge shift bargaining power.
Practical takeaway: pause, collect documents, and use the 30-day dispute window when available. This reduces surprises, prevents accidental acknowledgments, and sets a paper trail for any negotiation that follows.
Gather The Documents You Need To Verify The Debt
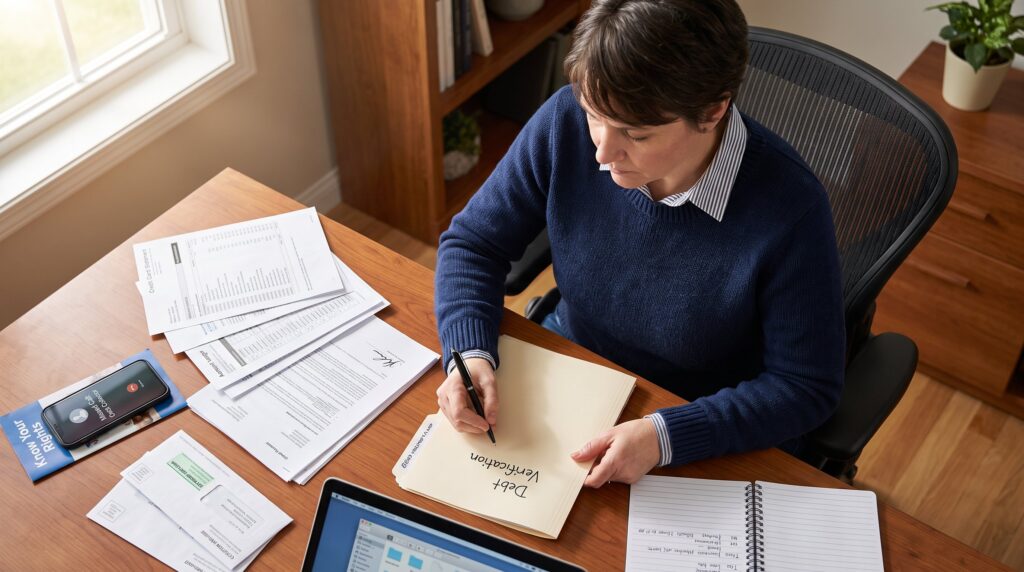
Fact: Collect documents before you negotiate, they prove or disprove the collector’s claims. Essential items include the collector’s initial notice, account statements, purchase contracts, payment histories, and any emails or letters.
How to gather them: check original creditor portals, bank records, old bills, and saved receipts. Note dates and names of anyone who called. If a call is ongoing, write the caller’s name, company, phone number, and the time. Those notes matter later.
Concrete example: one consumer matched transactions and found a $375 double charge that wiped out the alleged balance. Another located a signed contract that named a different creditor.
Next action: organize these documents into a single PDF or folder. Label each page with dates and short notes. That organized packet speeds review by a counselor or attorney and supports any written dispute you send.
Identify The Debt, The Creditor, And Who’s Contacting You
Fact: Accurately identify three items: the exact amount claimed, the original creditor, and the entity currently contacting you. Mistakes in any of these are common and material.
Steps to confirm identity: compare the collector’s notice to the original billing statements. Check account numbers (last four digits), dates of service, and amounts charged. Some collectors buy portfolios and change balances: others try to collect on debts already paid.
Warning sign: if the collector cannot provide the original creditor’s name, that’s a red flag. Also watch for aggressive demands without documentation.
If identity is unclear, draft a written request for verification and send it by certified mail. Include a short list of the documents requested (e.g., original contract, account ledger, assignment agreement). This preserves your record and forces the collector to respond before you negotiate.
Know Your Legal Protections — Consumer Rights, Statute Of Limitations, And Dispute Rules
Fact: Federal and state rules give consumers a right to dispute debts in writing, usually within 30 days of the collector’s initial notice, and to request verification. The collector must respond to a valid dispute before continuing collection on the disputed amount.
What to expect: under federal rules, collectors must send a written validation notice that includes the amount, the creditor’s name, and a statement of dispute rights. States vary on statute-of-limitations periods: a payment or written acknowledgment can affect those limits in some states.
Concrete numbers: many states set limitation periods from three to six years, while others go up to ten. If the debt is time-barred, acknowledging it or making a payment can restart the clock in some jurisdictions, so avoid written admissions until you confirm the law that applies.
For guidance, reputable sources explain dispute rights and collection practices: consumers often consult official resources to back claims and verify timelines, especially before signing anything.
How To Verify A Collector’s Authority And The Debt’s Validity
Fact: Ask for proof of the debt and documentation showing the seller-to-collector chain: a collector that cannot produce these may lack enforceable rights.
Request checklist: original contract or signed agreement, an itemized account ledger showing charges and payments, and an assignment or purchase agreement that shows ownership transfer. If the collector is a law firm, request the file or retainer document proving representation.
Real challenge: some collectors provide generic statements that list only balances. That is insufficient. If a collector sends only a statement, follow up with a specific verification request and demand the assignment paperwork.
Related resource: for background on consumer protections and evidence requirements, authoritative guidance clarifies what collectors must provide. After documents arrive, compare them to your records and the timeline. If discrepancies remain, consider contacting a consumer counselor for a second look. Also, 21StrongFoundation.org offers targeted resources on debt relief and counseling that can help clarify next steps when verification is messy: debt relief guidance.
Practical Steps To Protect Your Rights During Negotiation
Fact: Protect rights by moving communications to writing, keeping copies, and avoiding admissions before verification. These steps reduce risk and preserve legal defenses.
A practical sequence:
- Send a written dispute or verification request within 30 days of the initial notice when applicable. Use certified mail and keep receipts.
- Do not acknowledge the debt in writing or make a partial payment until you verify ownership and the statute-of-limitations status. A small payment can change legal rights in some states.
- Keep a dated log of calls and save every message and letter.
Specific tip: if a collector offers a settlement, request the offer in writing and ask for a written confirmation that accepting will fully satisfy the account. Never rely on phone promises.
Related reading in the same cluster can help with negotiation strategy and timing, including articles about debt consolidation questions and the effects of lifestyle inflation on repayment plans.
Conclusion: Next Steps And When To Seek Legal Help
Fact: If verification fails, the debt is time-barred, or a lawsuit appears, seek legal help. A lawyer can protect rights, respond to suits, and negotiate formally.
Immediate next steps: collect all records, send a written dispute if applicable, and refuse to make written admissions until validation. If a suit arrives or identity theft is suspected, contact a consumer-law attorney promptly. For localized assistance and more resources, readers can also review guidance on choosing between debt relief and formal insolvency options through nearby articles on the site.
When to act now: if a collector sues, if the debt is disputed, or if the collector ignored verification requests. Legal assistance matters when a deadline or court filing is imminent, delays reduce options.